Bengaluru and Erode, India — working with clients in other time zones

Services & technology

Finance & Insurance

RBI, SEBI, IRDAI and ICAI each set their own rules on what you may say. Calculators, forms and ads are built to the ones that apply to your business.

The problem

What makes this sector different

A borrower reads the Key Facts Statement, which sets out the APR and every charge, before signing a retail or MSME loan, and an insurance buyer checks the policy wording against what the ad said. What you may say depends on who regulates you: RBI for banks and NBFCs, SEBI for investment advisers, brokers and research analysts, and IRDAI for insurers and intermediaries. ICAI restricts how chartered accountants seek clients, and Google requires financial services verification before many financial ads run in India. Many enquiries also come from people who do not meet eligibility criteria, which uses up an adviser's calling time.

How the decision gets made. A retail borrower usually compares EMIs and Key Facts Statements from more than one lender, and the relationship manager or branch completes KYC and credit checks before sanction. An insurance buyer often reads the policy wording and claim terms before paying the first premium. For a business loan or group health policy, the finance head or HR recommends and a director or owner signs off.
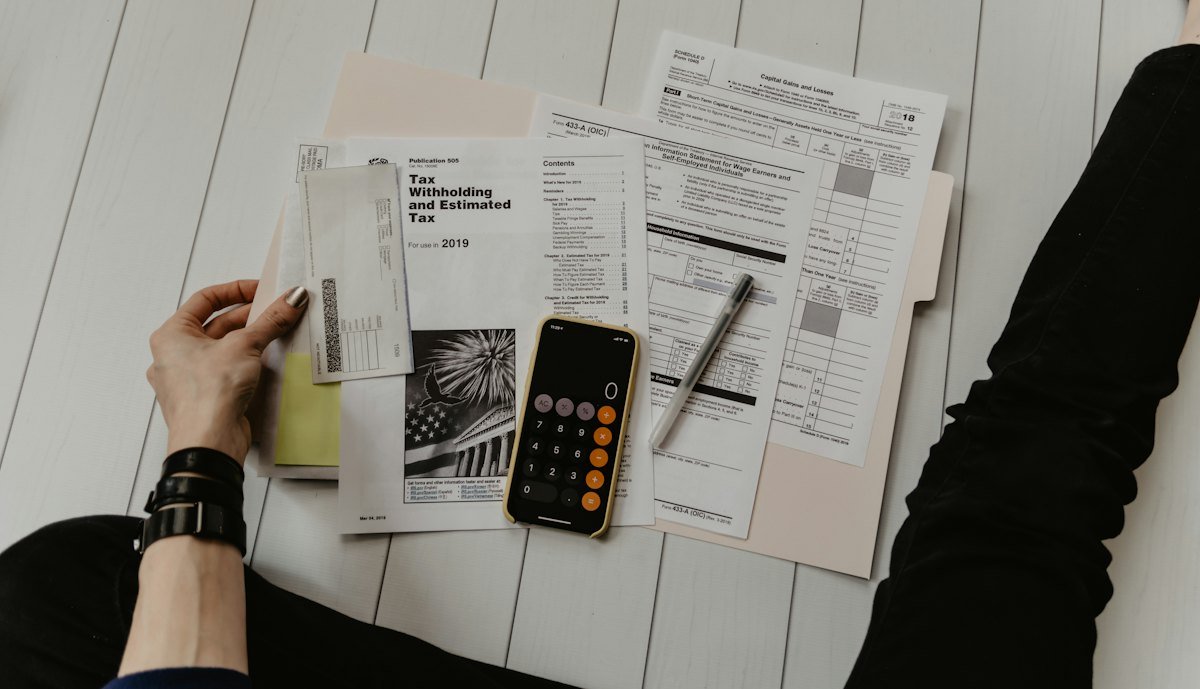
Hands sorting financial paperwork and forms with a calculator and pen on a white desk

Services in this sector

What each discipline does for finance & insurance

A lender's disclaimer has to fit on a WhatsApp creative, and an insurance ad has to carry its registration details even in a short reel. Your compliance team approves a template once, and every later creative is built on it.

Branding & Identity

An identity with a fixed place for the UIN, ARN and disclaimer

An insurance creative carries a registration number and UIN, a mutual fund distributor's post its ARN and market-risk statement, and a SEBI-registered adviser's page its registration number, where each applies. We design the logo, palette and typography with set positions for these details, so they stay legible on a WhatsApp square, a branch standee and a reel. The tone of voice guide rules out words such as 'guaranteed' unless the product terms support them.

  • Logo, palette and typography that keep figures and tables legible
  • Disclosure panel templates for UIN, ARN and registration numbers
  • Tone of voice guide with claims to avoid
About branding & identity

Web Design & UI/UX

EMI and SIP calculators that show the working

A borrower who tries your EMI calculator later compares the result with the APR in the Key Facts Statement, so each calculator states its rate, tenure and whether fees are included. SIP results are labelled as illustrations at an assumed return, beside the market-risk statement. Forms ask only what an adviser needs, and consent notices under the DPDP Act, grievance officer details and RBI Ombudsman information sit in the layout where they apply.

  • EMI calculator with rate, tenure and fee assumptions shown
  • SIP and premium illustrations with risk wording beside the result
  • Enquiry forms with DPDP consent notice and grievance details
About web design & ui/ux

Digital Marketing

Campaigns set to advance tax dates, 31 March and renewals

Advance tax falls due in June, September, December and March, tax-saving searches rise before 31 March, and motor and health policies renew on fixed dates. We plan search content and Google Ads around those dates and help you complete Google's financial services verification for India where it applies. Where you are SEBI-registered, influencer briefs stay within SEBI's bar on tie-ups with unregistered finfluencers who give advice or claim returns.

  • Advance tax, 31 March and policy renewal send schedule
  • Google Ads with financial services verification support
  • Influencer briefs checked against SEBI's finfluencer restrictions
About digital marketing

Digital Transformation

Loan and policy files that show what is still missing

A home loan file stalls for a week because salary slips arrived on WhatsApp and nobody marked them received. Each applicant's file shows the document checklist, KYC status and the Key Facts Statement issued. The file also records the consent and disclaimer version shown on the form. Renewal dates trigger reminders to the adviser, and bank statements can come through Account Aggregator where you are onboarded as a financial information user.

  • Applicant document checklist and KYC status per file
  • Consent and disclosure version record per lead
  • Renewal dates and missing documents flagged to the adviser
About digital transformation

Our approach

How we work in finance & insurance

01

We draft each page and ad to the disclosure rules that apply to your business, whether from RBI, SEBI, IRDAI or ICAI, and place registration numbers and disclaimers where a reader will see them.

02

We build EMI, SIP, premium and tax regime calculators that state their assumptions, and note that the APR in a Key Facts Statement includes fees an EMI estimate may leave out.

03

We add qualifying questions to enquiry forms, such as loan amount, city, employment type or policy renewal date, so advisers call eligible prospects first.

04

We keep a dated record of every creative and disclaimer version your compliance team approves, and of the version each lead saw.

Measurement

What we report on in this sector

Eligible enquiries by product and city

Calculator uses that lead to an enquiry

Loans sanctioned and policies issued, by channel

Questions

Finance & Insurance marketing, answered

Our ads are short reels. Where do the UIN, ARN and disclaimers go?
On screen inside the reel, not only in the caption, which many viewers never expand. An insurance reel shows the registration number and the product's UIN, a mutual fund distributor's reel shows the ARN, and the market-risk statement stays on screen long enough to read. We fix where each detail sits in a reel template, and your compliance team confirms the details for each product before it runs.
We are chartered accountants. Can we market our practice at all?
ICAI's Code of Ethics restricts how chartered accountants solicit clients, so the paid campaigns a lender or insurance intermediary might run are usually not an option. We work within what ICAI guidance allows, such as a factual website and articles published under your name, and ask you to check each item against the current guidance before it goes live.
Who holds the applicant details and consent records you collect?
You own the website, ad accounts, analytics and data, and we take no commission from any platform we recommend. That matters here, because under the Digital Personal Data Protection Act 2023 and the DPDP Rules 2025 your business is the data fiduciary for every applicant's details.

Next step

Working in finance & insurance?

Send us the problem in a paragraph. We will reply within one working day with a straight answer on whether we are the right agency for it.

Call +91 93451 90983 WhatsApp us